For ag retailers, finding ways to protect margins and differentiate their businesses has become increasingly important as the crop protection marketplace continues to evolve. One potential opportunity involves moving further upstream in the supply chain by becoming more directly involved in product manufacturing and formulation.
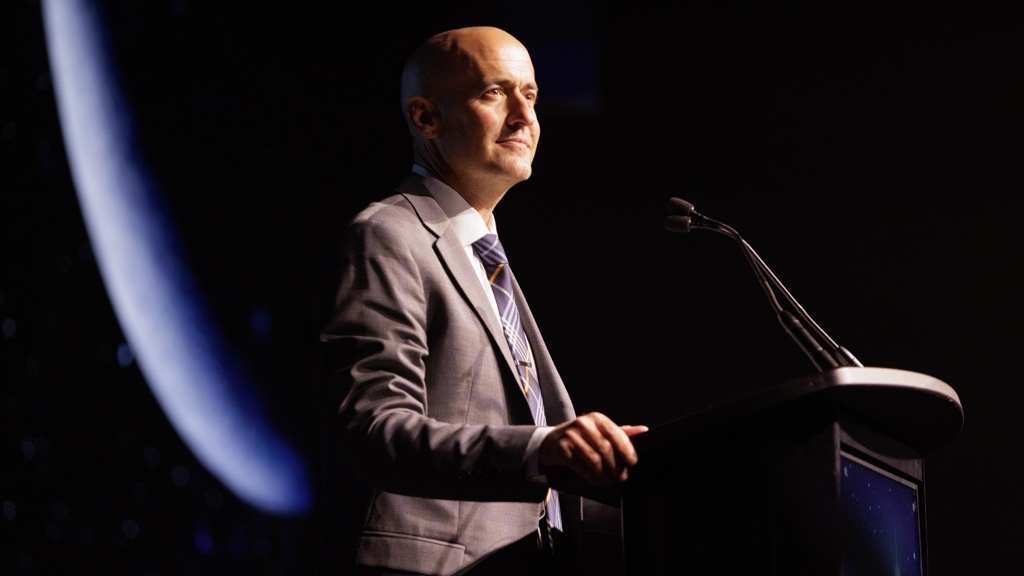
That was one of the key topics discussed during a recent episode of CropLife Retail Week, featuring Bob Trogele, CEO of ProAgInvest. During the conversation, Trogele explored how changing market dynamics, increased generic competition, and evolving distribution models could encourage some ag retailers to take a closer look at crop protection manufacturing.
Rather than simply purchasing finished products from manufacturers and reselling them to growers, some retailers may find opportunities to capture additional value by investing in capabilities that bring them closer to the production process.
“There are different models,” Trogele said. “Some companies may decide to deepen their relationships with certain manufacturers by investing in collaborative manufacturing ventures.”
Capturing More of the Supply Chain
As discussed during the interview, GROWMARK’s investment in its biological crop input manufacturing facility in St. Louis, MO, which uses precision fermentation to produce biological products, reflects a broader shift in how retailers participate in the supply chain. Rather than simply purchasing finished products from external suppliers, GROWMARK is taking a more active role in production, giving it greater influence over manufacturing, product development, and long-term supply reliability.
“They’re not buying finished product from a vendor. They’re creating their own formulation technology and therefore capturing that part of the upstream margin,” Trogele said.
For retailers, participation in manufacturing can create new opportunities to improve margins, differentiate product portfolios, and exert greater control over product development. More broadly, it signals a potential evolution in how ag retailers view their role within the crop protection supply chain, from distributors to strategic partners in product creation.
Of course, moving upstream requires significant capital investment, technical expertise, and a clear understanding of market demand, making it an impractical strategy for many retailers. Still, the examples highlighted by Trogele suggest that some larger organizations are increasingly willing to look beyond traditional distribution models in pursuit of new growth opportunities and competitive advantages.
New Competitors Are Entering the Market
Retailers considering upstream investments also need to recognize that they will be competing in an increasingly diverse marketplace.
Trogele pointed to Rainbow as an example of a company gaining attention through its investments in U.S. formulation capabilities.
“You’re bringing in really a Chinese active ingredient, formulating it in the United States, adding the value there,” he explained.
That type of investment illustrates how the generic crop protection business is becoming more sophisticated.
China has long been an important source of generic crop protection manufacturing. According to Trogele, the country now produces an estimated 60% to 70% of the generic chemical products in the marketplace.
But its influence is no longer limited to supplying active ingredients. Improvements in formulation technology and market access are helping Chinese companies become more competitive throughout the supply chain.
For ag retailers, this creates both opportunities and challenges. Greater competition could provide access to additional products and suppliers, but it could also put increased pressure on traditional distribution margins.
A Changing Distribution Landscape
Trogele believes the U.S. ag retail marketplace could eventually evolve into a more hybrid distribution environment, similar to what already exists in Brazil.
In that market, large agricultural producers sometimes have the purchasing power and infrastructure to operate much more independently of traditional distribution channels.
“If you go visit a large producer, he might be a $100 million customer in chemicals,” Trogele said.
These operations may have their own warehouses and agronomic staffs while purchasing products directly from manufacturers.
“He’s got his own warehouse, he’s got his own agronomic staff, and he’s buying direct from the vendor’s factory,” Trogele added.
At the same time, Brazil also has specialty growers and traditional distribution channels that include independent retailers and cooperatives.
Trogele sees the potential for similar diversification in the U.S., with different business models developing to serve different types of customers.
Some ag retailers may continue emphasizing traditional distribution and agronomic services. Others may explore private-label products, differentiated formulations, or manufacturing partnerships to create additional value.
He noted that some cooperatives are already looking for private-label opportunities and differentiated formulations that can help them move away from competing strictly on price.
The goal is to offer growers something beyond another product competing on cost alone.
Finding the Right Strategy
While upstream manufacturing could offer new opportunities, Trogele emphasized that ag retailers will need to make deliberate decisions about where they want to compete and how they intend to generate profits.
He believes the industry is entering a period of significant change, with traditional distribution models facing pressure from new competitors and alternative approaches to serving growers.
“We’re going to be a little bit in transition,” Trogele said. “We’re going to be a hybrid market, like Brazil.”
Manufacturing and formulation investments could represent another way for certain retailers to differentiate their businesses and capture additional value. However, those investments must fit into a broader business strategy.
As Trogele noted, “I think it’ll take a couple of years to settle. And everybody will be positioned at what they do best.”
For ag retailers, that may mean rethinking their traditional roles in the crop protection supply chain and considering whether there are opportunities to capture more value by moving upstream.
Want to hear more from Bob Trogele?
Be sure to watch the full episode of CropLife Retail Week featuring Trogele. In addition to the discussion about ag retailers exploring crop protection manufacturing, the conversation covers the growing influence of generic crop protection products, upcoming patent expirations, the potential impact of Federal Trade Commission actions, changing supplier relationships, inventory management challenges, and how retailers can position their businesses for an increasingly competitive marketplace.